Love, Lies, and Secret Bank Accounts: Is Financial Privacy Just Cheating with a Calculator?
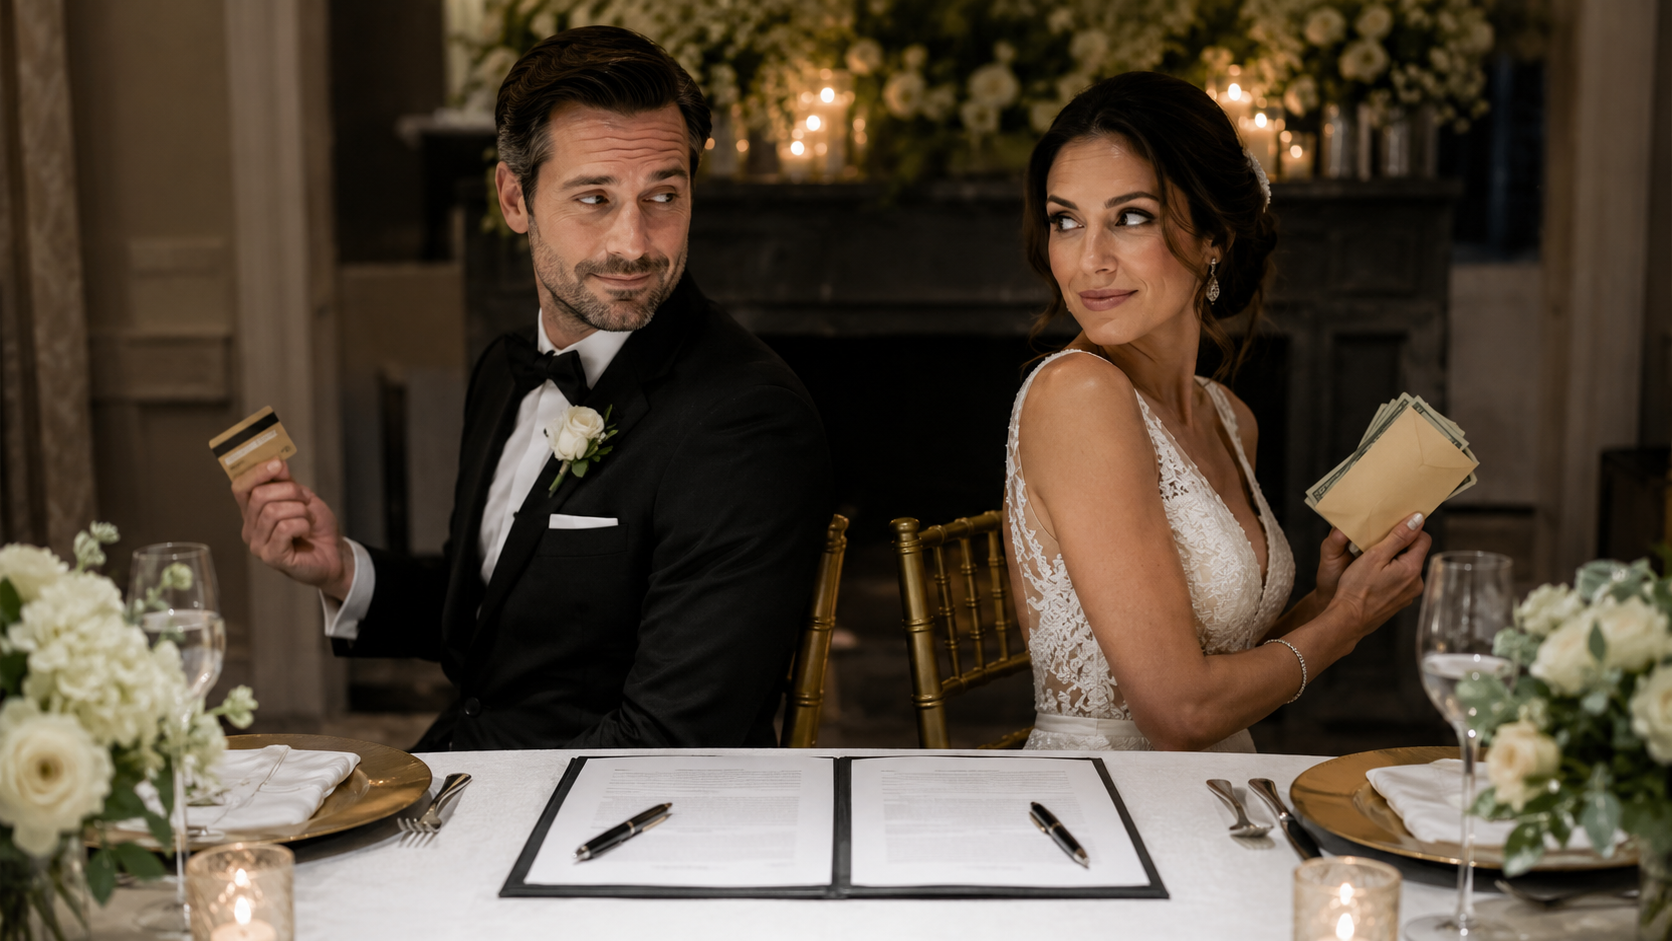
They agreed to full financial transparency—except for the parts involving money.
Marriage is built on trust, communication, commitment, and apparently one credit card your spouse thinks was canceled in 2023.
Modern couples will share a bed, a bathroom, bodily fluids, streaming passwords, and one terrifying family group chat—but ask to see the bank statement and suddenly everybody becomes a constitutional scholar. “I am entitled to financial privacy.” Sure. You’re also carrying $18,000 in secret debt and just classified a bass boat as an emergency expense.
Money has always made relationships weird. The difference now is that people are finally admitting it. WalletHub’s 2026 Money & Relationships Survey found that 75% of Americans believe a prenup is good for a relationship. Very mature. Very responsible. The same survey found that 26% have a financial account their partner doesn’t know about.
So three out of four people support honest planning, while one out of four is quietly running a financial witness-protection program.
A Prenup Is Not a Divorce Reservation
Mention a prenup and somebody immediately reacts like you asked the wedding DJ to reserve a breakup song.
“Why are you planning for divorce before we’re even married?”
Because adults plan for unpleasant possibilities. That’s why we buy insurance, write wills, wear seatbelts, and don’t hand fireworks to the drunk uncle. Nobody screams, “You bought homeowners insurance? So you’re already planning to burn down our love nest?”
A prenup is a financial agreement made while two people still like each other. That is the best possible time to discuss what happens if one day they communicate exclusively through attorneys and passive-aggressive Venmo requests.
It doesn’t mean the richer partner believes the poorer partner is a gold digger. Sometimes it means one person has a business, property, children from a previous relationship, family assets, or debt they don’t want dumped into the marital punch bowl. Sometimes both people simply want expectations written down before resentment, lawyers, and somebody’s mother turn the divorce into a low-budget civil war.
And yes, men can get weird about prenups. A guy with a financed pickup, $312 in checking, and a collection of commemorative whiskey bottles starts acting like Jeff Bezos when his fiancée mentions protecting her house. “She’s only after my money.” Sir, the bank owns your truck, Klarna owns your television, and your retirement plan is apparently “hit a parlay.” Nobody is infiltrating the bloodline for your air fryer.
Women can get offended too. “If he loved me, he wouldn’t need one.” Love is not a legal strategy. Love is the reason you’re getting married. Paperwork is what protects both people if love eventually puts on sweatpants, starts sleeping in another room, and says, “My attorney will be in touch.”
WalletHub’s finding that 75% view prenups positively suggests the stigma is fading. Good. People are marrying later, arriving with assets and obligations, and understanding that romance does not erase arithmetic. But a prenup must be fair, transparent, properly handled, and reviewed under the laws where you live. This is a comedy blog, not legal advice; get independent attorneys instead of downloading “Totally Legit Prenup FINAL_v7.pdf” from some guy named Chad.
The real question isn’t whether discussing a prenup is unromantic. The question is why financial clarity feels less romantic than lying politely until the reception deposit becomes nonrefundable.
Separate Money Is Privacy; Secret Money Is a Hostage Situation
Couples do not need to combine every dollar. The “yours, mine, and ours” system can make perfect sense: one shared account for bills and goals, plus separate accounts for personal spending. That way nobody has to convene a congressional hearing because somebody bought golf clubs, concert tickets, or a decorative pillow that contributes nothing except occupying the exact spot where a man wanted to sit.
Privacy is agreed upon. Secrecy is concealed.
If both partners know each person keeps a separate account, that’s independence. If your spouse discovers the account while searching for tax documents and you begin sweating like a youth pastor at a browser-history audit, that’s financial infidelity.
The 2026 WalletHub survey found that 26% of Americans have an account their partner doesn’t know about. Bankrate’s 2025 survey went wider: 40% of adults in committed relationships said they had committed some form of financial infidelity against their current partner. That included overspending, secret debt, hidden credit cards, and undisclosed accounts.
Forty percent. Nearly half the country is apparently operating a romantic relationship and a shell corporation.
The most common secret was spending more than the partner would approve of. We all know that move. A suspicious package arrives, and suddenly someone is delivering a TED Talk about how much money they “saved.” You did not save $300 by spending $700. That is not saving. That is being mugged by a coupon.
Then there is secret debt—the relationship land mine. You can hide a balance during dating because nobody puts “$27,000 at 29.99% APR” between hiking and loving tacos on a profile. But once you combine a household, debt affects shared goals. The down payment disappears. The vacation becomes a weekend near an interstate exit. Retirement moves from age 65 to “hopefully before death.”
Of course, not every hidden account comes from selfishness. Some people keep emergency money because they fear financial control or need a safe route out of an abusive relationship. That is a completely different situation and should not be mocked or treated like ordinary dishonesty. Safety comes first.
But “I needed a secret account for safety” is not the same as “I needed a secret account because my wife would ask why I spent $900 on vintage sneakers.” One is protection. The other is an adult hiding cookies behind the washing machine.
Financial Cheating Doesn’t Leave Lipstick—It Leaves Interest Charges
Bankrate’s 2026 survey found that 43% of Americans believe keeping financial secrets is at least as bad as physical infidelity. Five percent said it is worse.
That sounds dramatic until you imagine discovering your spouse didn’t sleep with a coworker—they merely opened three cards, emptied the emergency fund, stopped paying the mortgage, and financed a motorcycle using your shared address. At least an affair might end after a screaming match. Compound interest keeps showing up every month like a dedicated little bastard.
Financial infidelity hurts because money represents more than money. It represents safety, time, choices, and future plans. Every hidden purchase says, “My immediate desire mattered more than the agreement we made.” Every secret debt says, “I borrowed from our future without asking.” Every lie about income says, “I wanted control over information that affects both of us.”
That’s why discovering financial deception can feel like discovering an affair. The betrayal is not the dollar amount alone; it is learning that the household you thought you shared had a secret basement.
Fidelity’s couples research keeps finding gaps between what partners think they know and what they actually know. Its 2024 study reported that 45% of partners argue about money at least occasionally. Fidelity has also reported that more than a third of spouses don’t know what their partner earns, while more than half disagree about how much they need for retirement.
How are you planning forever when neither person knows what the other makes or what forever costs? That’s not a financial plan. That’s two people driving into fog while arguing over who controls the radio.
And couples are spectacular at avoiding the conversation. Nobody wants to ruin date night by asking about credit scores. We’d rather discuss exes, childhood trauma, politics, religion, sexual preferences, and whether pineapple belongs on pizza before asking, “Do you pay your card in full?” Apparently, exchanging bodily fluids is less intimate than revealing the APR.
WalletHub found 72% believe financial disagreements are worse for a relationship than political disagreements, and 80% consider poor financial literacy a turnoff. That means people know money matters. They just wait until they’re emotionally invested, sharing a lease, and arguing beside a broken water heater to discuss it.
Have you ever hidden a purchase because you knew your partner would be pissed? Did you call it privacy, or did you know damn well it was deception? And where is the line—a $50 splurge, a $500 purchase, a secret card, or any lie at all?
The Money Talk Is Unsexy—Until the Lies Get Expensive
Financial honesty does not require two adults to surrender every bit of independence. It requires them to agree on the rules before somebody breaks them.
Start with the ugly numbers: income, debt, credit problems, support obligations, major assets, and financial goals. Not on the first ten minutes of a coffee date—nobody wants foreplay featuring a student-loan dashboard—but certainly before marriage, a mortgage, or combining accounts.
Decide what stays separate, what becomes joint, and which purchases require a conversation. One couple might agree that anything under $200 is personal. Another may need a $50 limit because their budget is tighter than jeans after Thanksgiving. The number matters less than both people knowing it.
Then hold regular budget check-ins. Yes, it sounds painfully adult. Nobody has ever dimmed the lights and whispered, “Baby, open the spreadsheet.” But twenty minutes reviewing bills beats three hours screaming because the shared account is missing enough money to qualify for an Amber Alert.
And stop using income as a weapon. The higher earner is not the household dictator. The lower earner is not automatically irresponsible or less valuable. Fidelity’s 2026 findings said 58% of couples report unequal household financial contributions, and nearly one in four say that imbalance affects the relationship. A relationship cannot function if every disagreement ends with someone slamming a pay stub on the table like a royal decree.
For prenups, discuss them early. Not six days before the wedding while Grandma is assembling centerpieces and one partner feels financially ambushed. Each person should have independent legal advice, full disclosure, and enough time to understand the agreement. The goal is clarity, not slipping a contract between the rehearsal dinner and the chicken dance.
For separate accounts, be separate—not secret. “I have my own spending account” is healthy information. “I have my own spending account in another state under my middle name” is the opening scene of a documentary.
The point is not that every couple should merge everything or sign a prenup. The point is that both people should know what game they are playing. You cannot call it teamwork when one person has a hidden scoreboard.
So, are prenups practical or insulting? Should married couples be entitled to accounts the other person cannot see? What counts as financial cheating in your relationship—and would secret debt hurt more than a physical affair?
Drop your answer in the comments. This topic should be discussed before the proposal, not after somebody finds a bank statement tucked inside the air-fryer manual.
Follow Whiskey’d & Uncensored on our socials, catch up on previous blogs, and share this post with your friends and favorite sites. Sometimes a friend needs the truth—especially the one calling a hidden credit card “self-care.” If you enjoyed the post, please consider a donation below to help offset the cost of these ever-growing expensive servers. These aren’t paid posts, and every little bit keeps the entertainment flowing. Give us your thoughts and opinions in the comments!
Also, don’t forget to stop by whiskeydanduncensored.com/fun-custom-products for all-new, fun, lighthearted products that prove you have an excellent sense of humor.
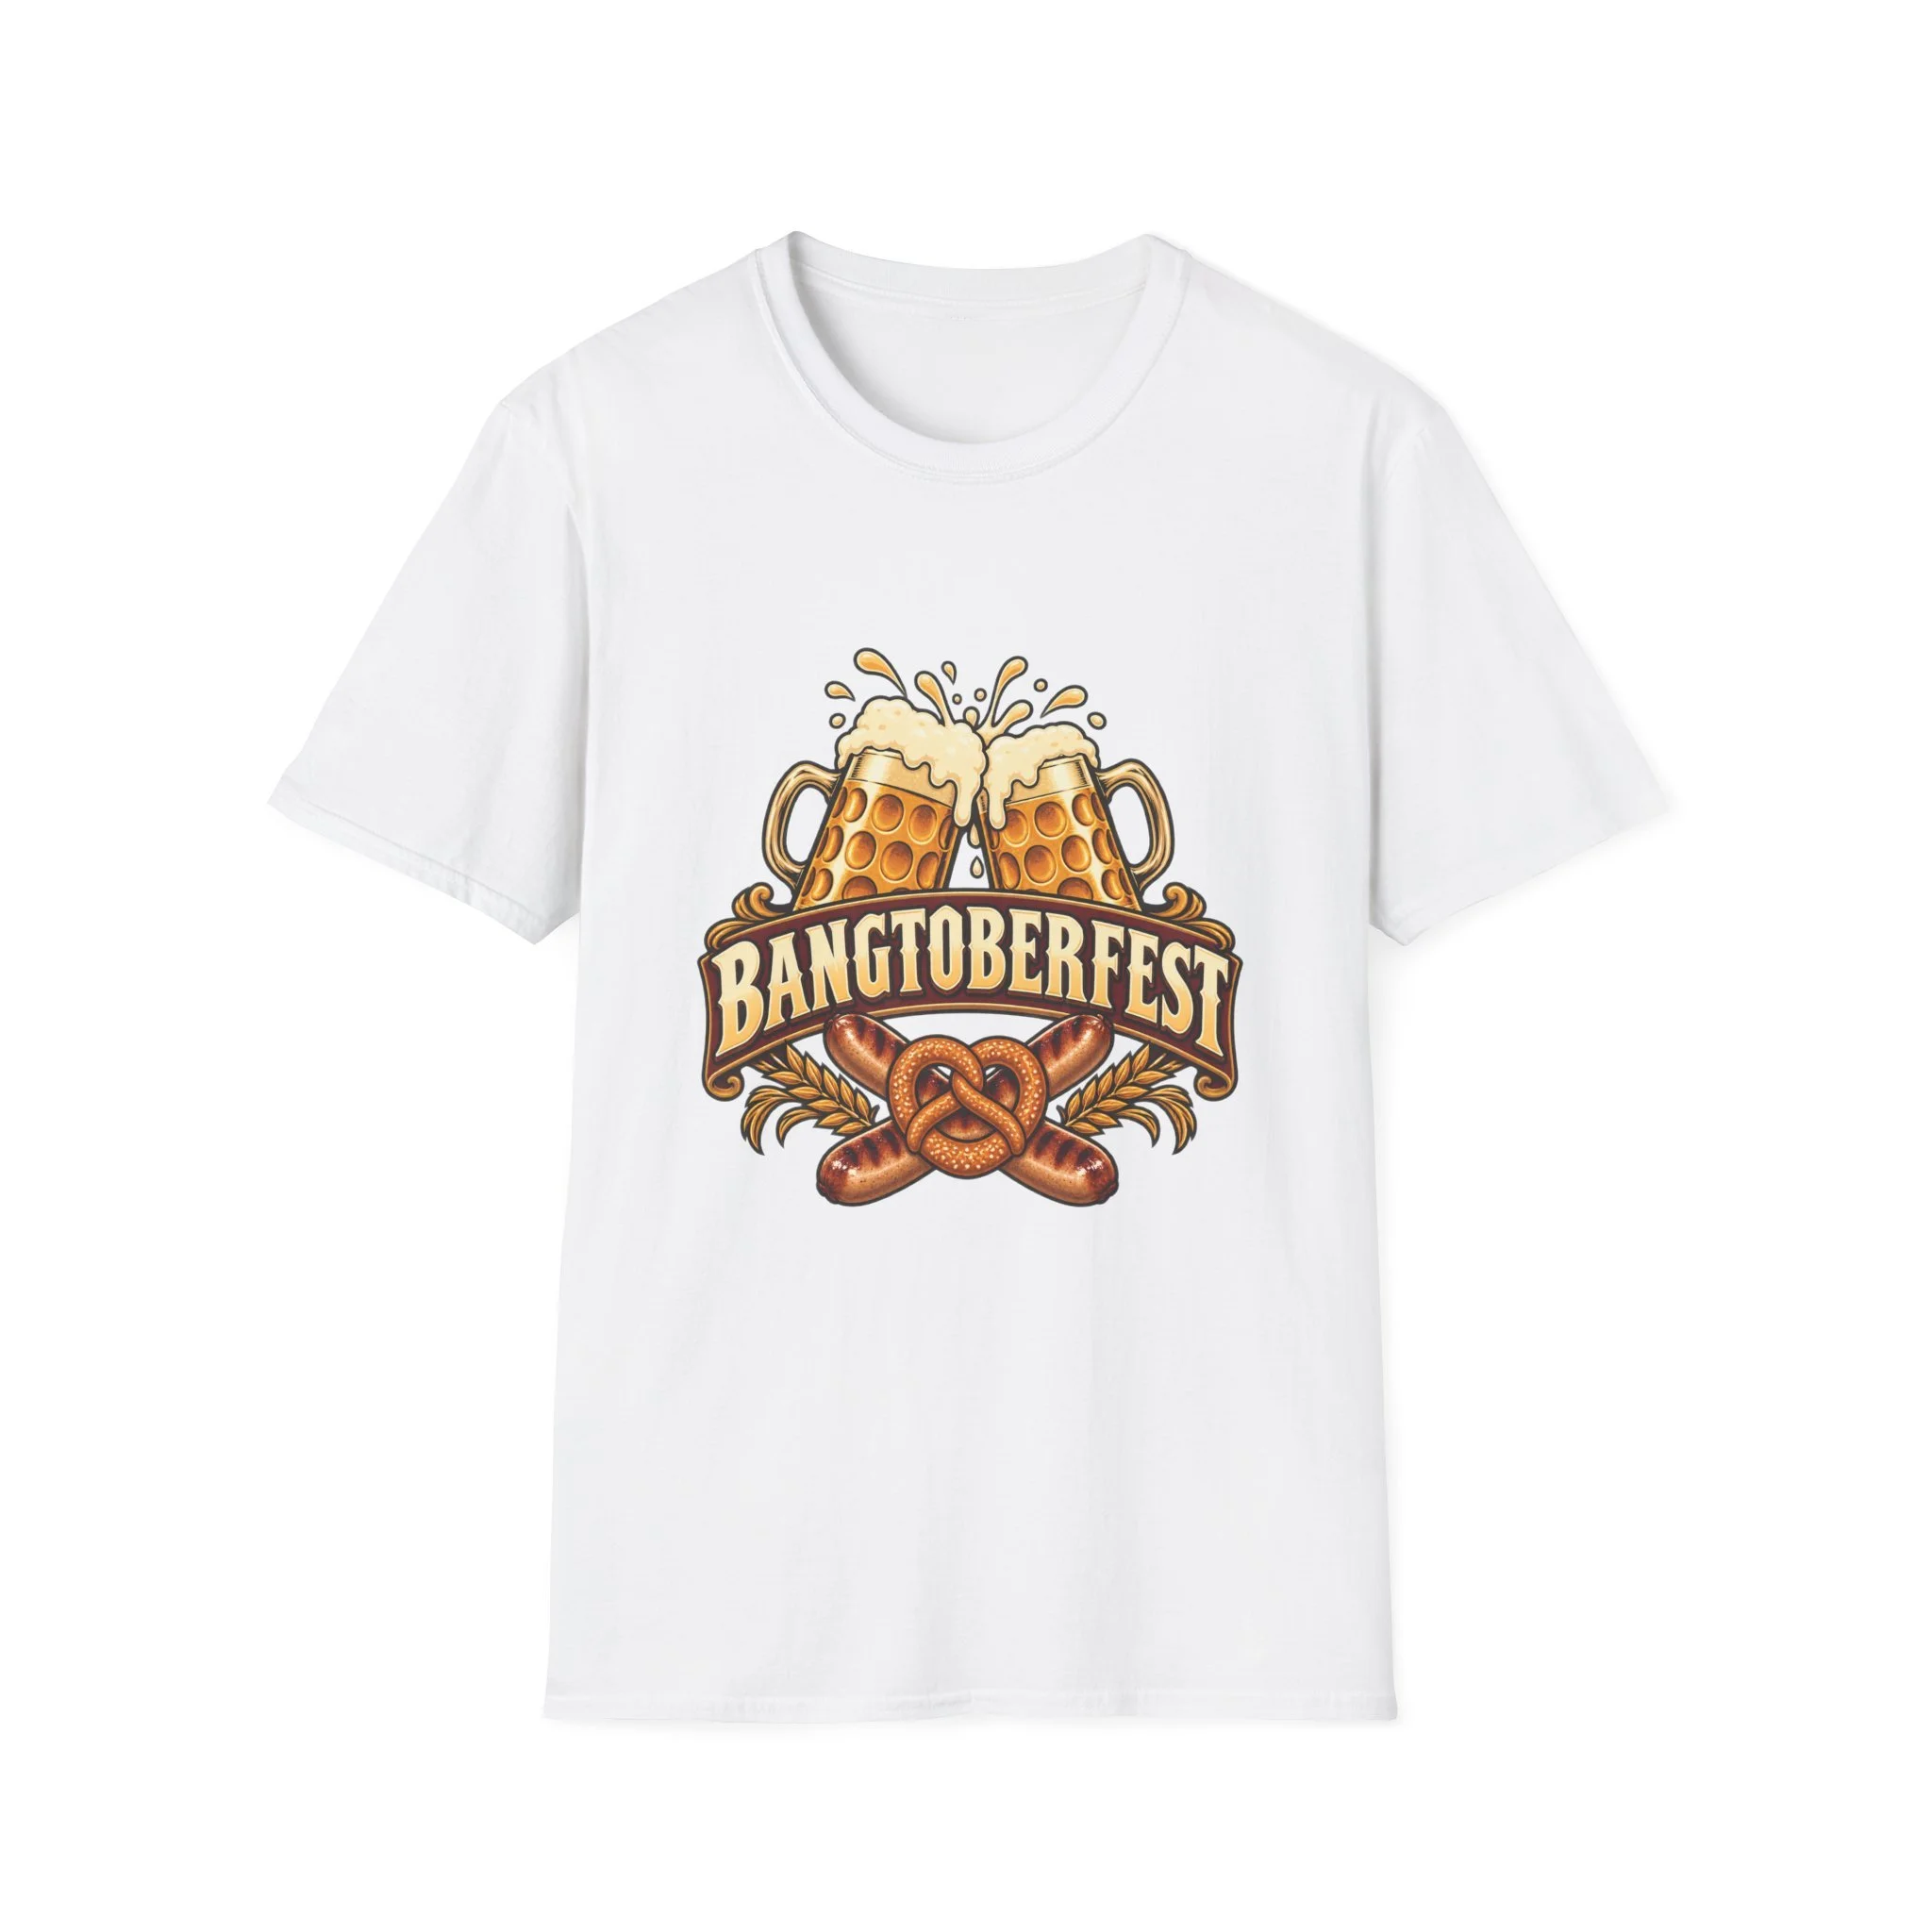
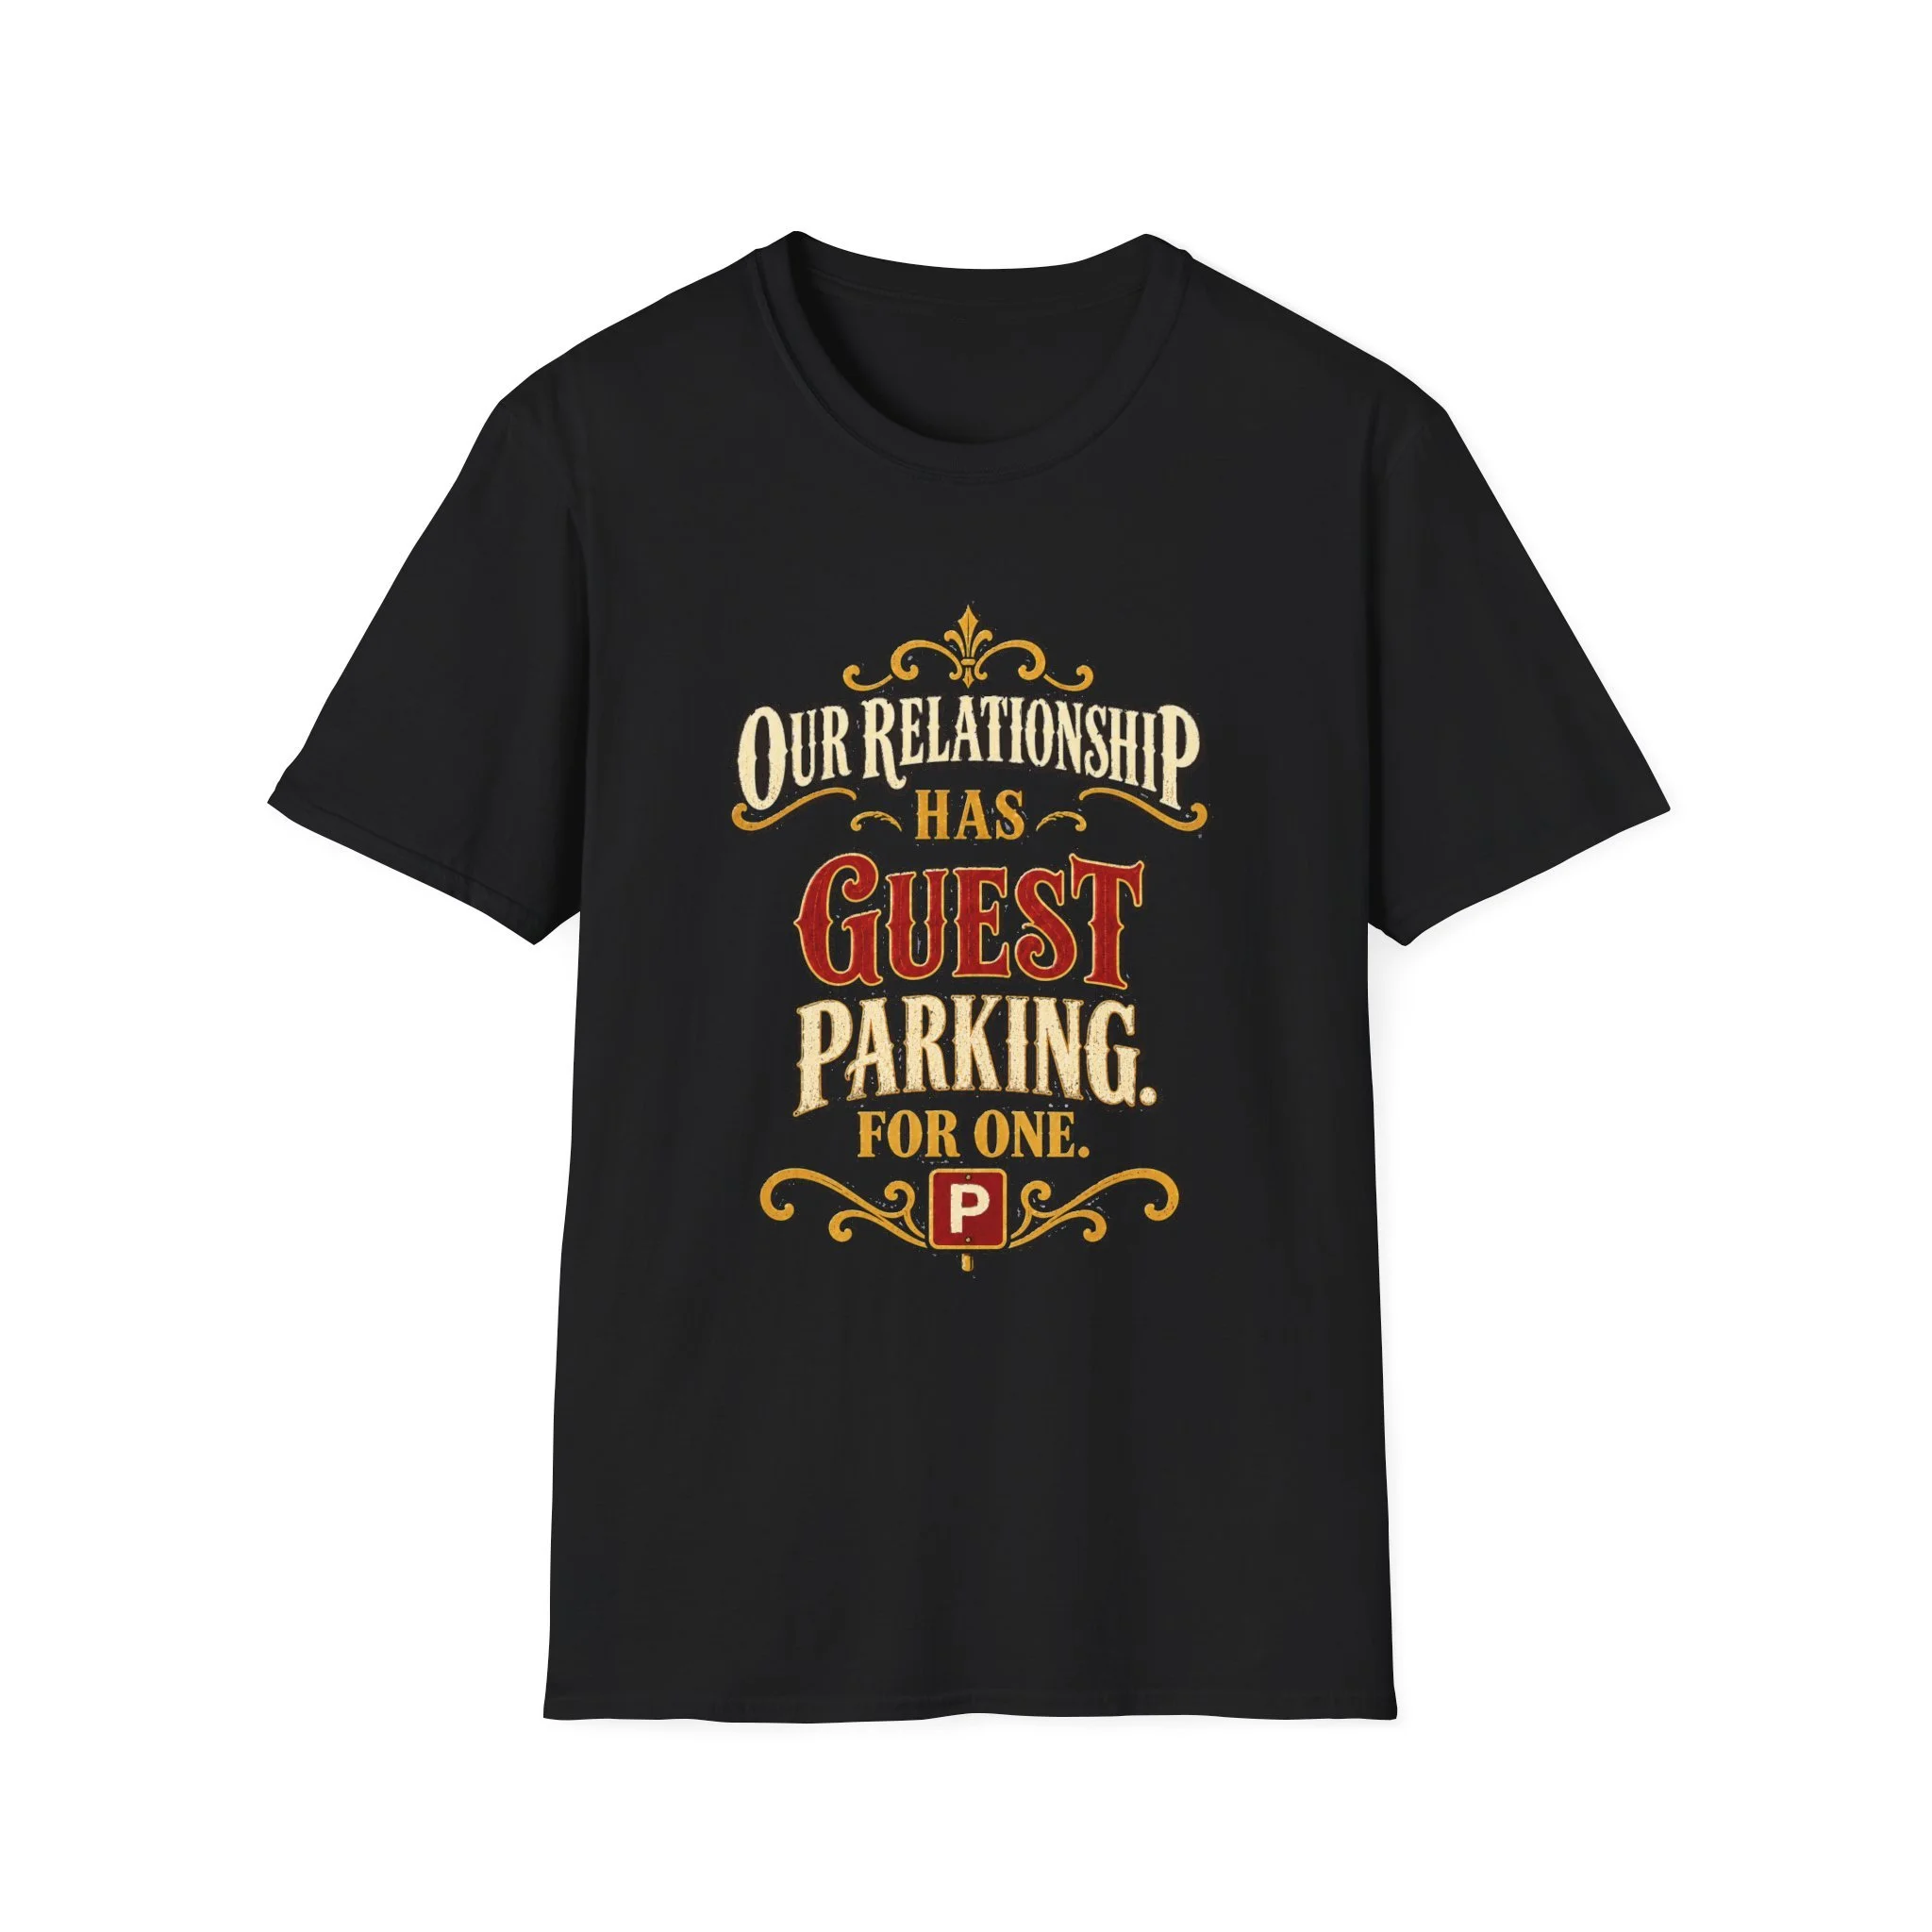
Product features
- 100% ring-spun cotton (lightweight 153 g/m²) — soft and breathable
- Tubular knit with no side seams for a smooth, waste-reducing fit
- Ribbed collar with shoulder tape to hold shape and prevent stretching
- Print methods: Direct-to-Garment for main art; Direct-to-Film for sleeve/neck details
- OEKO-TEX® STANDARD 100 certified and EU 2-year warranty
Care instructions
- Do not dryclean
- Do not bleach
- Tumble dry: low heat
- Iron, steam or dry: low heat
- Machine wash: cold (max 30C or 90F), with similar colors